US citizens owe federal tax on income earned anywhere in the world. That includes income earned while living and working abroad full time. This guide walks through the filing steps: whether you still need to file, and which tax break lowers your bill. It also covers FBAR, FATCA, self-employment tax, and state residency, the areas where remote workers most often get tripped up.
1. Confirm you still have to file
The US taxes citizens on worldwide income, no matter where they live. This is called citizenship-based taxation, and moving abroad doesn’t end the filing requirement.
- Filing threshold: Gross income above $15,000 for the 2025 tax year triggers this requirement, the same amount used at home.
- Foreign income counts: Wages, freelance pay, and self-employment income from a foreign client all count toward the threshold. It doesn’t matter if the money stays in a foreign account.
- No US income required: A filing obligation can exist with zero US-source income, since the rule is based on worldwide earnings.
The filing requirement and the tax bill are separate questions. Most remote workers abroad end up owing little after exclusions apply, but the paperwork still has to be filed.
2. Mark down your three deadlines
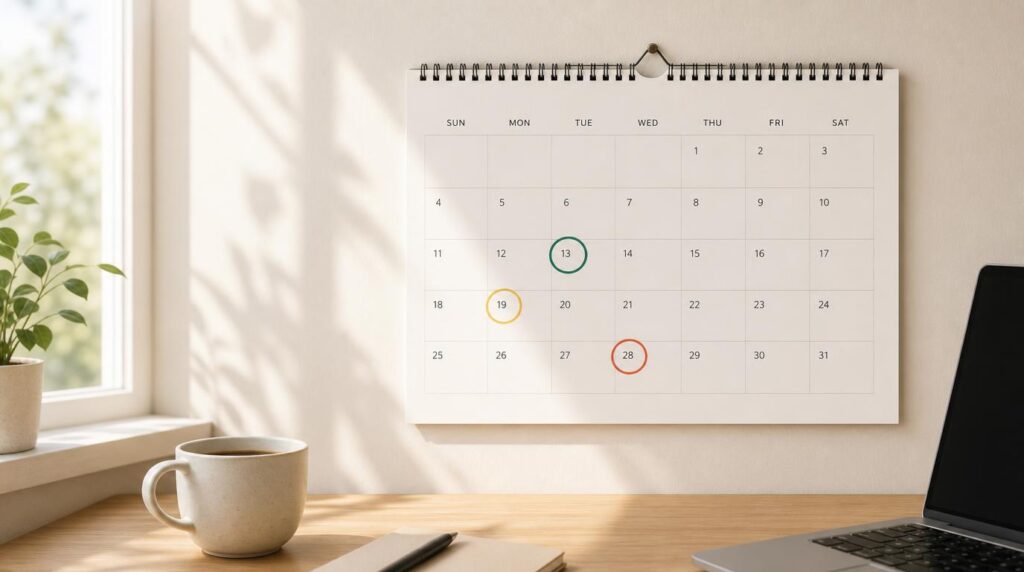
US citizens abroad work with three key dates, not one. Mixing them up is a common way expats end up owing interest they didn’t expect.
- April 15: Any tax owed for the year is due on this date, no matter where you live. Interest starts building from here even if you file later.
- June 15: Citizens whose tax home is abroad on April 15 get an automatic two-month extension. No extra form is required.
- October 15: Filing Form 4868 before June 15 pushes your filing deadline further, to this date. Any balance owed is still due back in April.
The extensions only cover filing the paperwork. A tax bill left unpaid after April 15 accrues interest the whole time, even with a valid extension.
3. Decide between the Foreign Earned Income Exclusion and the Foreign Tax Credit
Two separate tools reduce US tax on income already earned abroad. Picking the wrong one for a given year can mean paying more than necessary.
- Foreign Earned Income Exclusion (FEIE): Excludes up to $130,000 of foreign earned income for the 2025 tax year. The limit rises to $132,900 for 2026 income, filed in 2027. Claimed on Form 2555.
- Qualifying tests: Meet the Physical Presence Test, 330 full days outside the US in any 12-month period. Or meet the Bona Fide Residence Test, a full calendar year of established residence abroad.
- Foreign Tax Credit (FTC): A dollar-for-dollar credit for income tax already paid abroad, claimed on Form 1116. Often the stronger option in a higher-tax country.
- No double dipping: The same income can’t be excluded under the FEIE and credited under the FTC at once.
The FEIE tends to win in low-tax or no-tax countries like the UAE. The FTC often works out better in higher-tax countries like Germany, since unused credit carries forward for future years.
4. Separate self-employment tax from your income tax bill
The FEIE only shelters income tax. It does nothing for self-employment tax, and freelance nomads often get caught out here.
- Rate: Self-employed remote workers owe 15.3% on net earnings above $400, covering Social Security and Medicare. This applies on top of any income tax owed.
- Applies even with full FEIE coverage: A freelancer who excludes their income under the FEIE can still owe thousands in self-employment tax.
- Totalization agreements: The US has agreements with more than 30 countries, including the UK, Germany, and Japan. These can exempt a self-employed filer from US self-employment tax when paying into the other country’s system instead. This generally requires actual residence there and a certificate of coverage, which constant country-hopping makes hard to get.
Someone earning $100,000 in freelance income abroad, with zero income tax owed, can still face over $14,000 in self-employment tax. Quarterly payments on Form 1040-ES help avoid a penalty at filing time.
5. Check whether FBAR or FATCA applies to your accounts
Two separate reporting rules apply to foreign bank accounts, and neither one is a tax. Both carry real penalties, even when no tax is owed.
- FBAR (FinCEN Form 114): Required once combined foreign account balances cross $10,000 at any point in the year. Even a single day above the line counts. Filed with the Treasury, separate from your tax return, due April 15 with an automatic extension to October 15.
- FATCA (Form 8938): Filed with your IRS return if foreign assets exceed $200,000 at year-end for a single filer abroad. The threshold is $300,000 if assets peaked higher at any point. The thresholds double for a married couple filing jointly.
- Both can apply at once: A modest Wise or Revolut balance over $10,000 can trigger the FBAR. It takes a much larger balance to trigger FATCA.
Related: how to open a bank account without residency as a digital nomad
Non-willful FBAR penalties run over $16,000 per violation. Check both thresholds annually, since they can shift from one year to the next.
6. Sort out state tax residency before you leave
Federal rules get most of the attention, but a home state can keep taxing a remote worker who thinks they’ve already left.
- Sticky states: California, New York, and Virginia are known for closely scrutinizing residency claims from people who moved abroad.
- What actually breaks residency: Selling or renting a home, changing a license and voter registration, and moving belongings out show real departure.
- No income tax states: Setting up residency in Florida, Texas, or another no-tax state before moving abroad avoids this question later.
A remote worker who keeps a license, a voter registration, and a lease in a high-tax state hands that state an argument. Residency, in that state’s eyes, hasn’t really ended.
Common mistake: assuming the FEIE cancels US taxes entirely
The most common misunderstanding treats the Foreign Earned Income Exclusion as a blanket exemption from US taxes. It excludes earned income from income tax, and nothing more. Self-employment tax still applies in full. Investment income, rental income, and capital gains aren’t covered by the exclusion at all. Someone might earn $60,000 freelancing and make a $20,000 stock gain in the same year. The freelance income could owe zero tax under the FEIE. The stock gain still owes capital gains tax.
This is general information, not individual tax advice, and rules change from year to year. Confirm current thresholds and forms with a tax professional who specializes in expat returns, or directly with the IRS, before filing. This article reflects information verified as of September 2026.
Filing from abroad takes more paperwork than filing from home. The math still works in favor of most remote workers once the FEIE, FTC, and self-employment tax pieces are sorted out correctly. A tax professional who specializes in expat returns is worth the fee in the first year. They can confirm the qualifying test and the FBAR threshold are handled right. Once your paperwork is in order, the destination side gets easier too. Search flights on FlyBibe and get moving on wherever the work takes you next.